Page 23 - 2board23full
P. 23
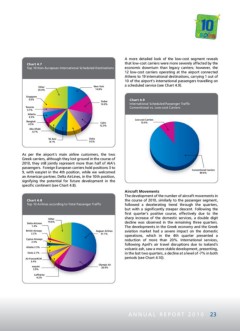
Chart 4.7 A more detailed look of the low-cost segment reveals
Top 10 Non-European International Scheduled Destinations that low-cost carriers were more severely affected by the
economic downturn than legacy carriers; however, the
12 low-cost carriers operating at the airport connected
Athens to 19 international destinations, carrying 1 out of
10 of the airport’s international passengers travelling on
a scheduled service (see Chart 4.9).
Chart 4.9
International Scheduled Passenger Traffic
Conventional vs. Low-cost Carriers
As per the airport’s main airline customers, the two Aircraft Movements
Greek carriers, although they lost ground in the course of The development of the number of aircraft movements in
2010, they still jointly represent more than half of AIA’s the course of 2010, similarly to the passenger segment,
passengers. Foreign European carriers hold positions 3 to followed a decelerating trend through the quarters,
9, with easyJet in the 4th position, while we welcomed but with a significantly steeper descent. Following the
an American partner, Delta AirLines, in the 10th position, first quarter’s positive course, effectively due to the
signifying the potential for future development in the sharp increase of the domestic services, a double digit
specific continent (see Chart 4.8). decline was observed in the remaining three quarters.
The developments in the Greek economy and the Greek
Chart 4.8 aviation market had a severe impact on the domestic
Top 10 Airlines according to Total Passenger Traffic operations, which in the 4th quarter presented a
reduction of more than 20%. International services,
following April’s air travel disruptions due to Iceland’s
volcanic ash, saw a more stable development, presenting,
in the last two quarters, a decline at a level of -7% in both
periods (see Chart 4.10).
A N N U A L R E P O R T 2 0 1 0 23
Top 10 Non-European International Scheduled Destinations that low-cost carriers were more severely affected by the
economic downturn than legacy carriers; however, the
12 low-cost carriers operating at the airport connected
Athens to 19 international destinations, carrying 1 out of
10 of the airport’s international passengers travelling on
a scheduled service (see Chart 4.9).
Chart 4.9
International Scheduled Passenger Traffic
Conventional vs. Low-cost Carriers
As per the airport’s main airline customers, the two Aircraft Movements
Greek carriers, although they lost ground in the course of The development of the number of aircraft movements in
2010, they still jointly represent more than half of AIA’s the course of 2010, similarly to the passenger segment,
passengers. Foreign European carriers hold positions 3 to followed a decelerating trend through the quarters,
9, with easyJet in the 4th position, while we welcomed but with a significantly steeper descent. Following the
an American partner, Delta AirLines, in the 10th position, first quarter’s positive course, effectively due to the
signifying the potential for future development in the sharp increase of the domestic services, a double digit
specific continent (see Chart 4.8). decline was observed in the remaining three quarters.
The developments in the Greek economy and the Greek
Chart 4.8 aviation market had a severe impact on the domestic
Top 10 Airlines according to Total Passenger Traffic operations, which in the 4th quarter presented a
reduction of more than 20%. International services,
following April’s air travel disruptions due to Iceland’s
volcanic ash, saw a more stable development, presenting,
in the last two quarters, a decline at a level of -7% in both
periods (see Chart 4.10).
A N N U A L R E P O R T 2 0 1 0 23