Page 90 - 2board23full
P. 90
Financial Statements
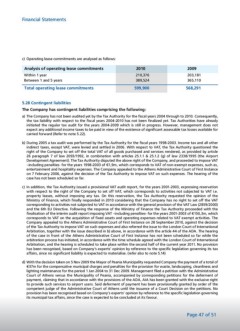
c) Operating lease commitments are analysed as follows: 2010 2009
Analysis of operating lease commitments 210,376 203,181
389,524 365,110
Within 1 year
Between 1 and 5 years 599,900 568,291
Total operating lease commitments
5.28 Contingent liabilities
The Company has contingent liabilities comprising the following:
a) The Company has not been audited yet by the Tax Authority for the fiscal years 2004 through to 2010. Consequently,
the tax liability with respect to the fiscal years 2004-2010 has not been finalized yet. Tax Authorities have already
initiated the regular tax audit for the years 2004-2009 which is still in progress. However, management does not
expect any additional income taxes to be paid in view of the existence of significant assessable tax losses available for
carried forward (Refer to note 5.22).
b) During 2005 a tax audit was performed by the Tax Authority for the fiscal years 1998-2003. Income tax and all other
indirect taxes, except VAT, were levied and settled in 2006. With respect to VAT, the Tax Authority questioned the
right of the Company to set off the total VAT of all goods purchased and services rendered, as provided by article
26 paragraph 7 of law 2093/1992, in combination with articles 25.1.1 & 25.1.2 (g) of law 2338/1995 (the Airport
Development Agreement). The Tax Authority disputed the above right of the Company, and proceeded to impose VAT
–including penalties- for the years 1998-2003 of €1,9m, which corresponds to VAT of non-exempt expenses, such as,
entertainment and hospitality expenses. The Company appealed to the Athens Administrative Court of First Instance
on 7 February 2006, against the decision of the Tax Authority to impose VAT on such expenses. The hearing of the
case has not been scheduled so far.
c) In addition, the Tax Authority issued a provisional VAT audit report, for the years 2001-2003, expressing reservation
with respect to the right of the Company to set off VAT, which corresponds to activities not subjected to VAT i.e.
property leases, without imposing any tax. On this reservation, the Tax Authority requested the opinion of the
Ministry of Finance, which finally responded in 2010 considering that the Company has no right to set off the VAT
corresponding to activities not subjected to VAT in accordance with the general provision of the VAT Law (2859/2000)
and the 6th EU Directive. Following the response of the Ministry of Finance the Tax Authority proceeded with the
finalisation of the interim audit report imposing VAT –including penalties- for the years 2001-2003 of €150,3m, which
corresponds to VAT on the acquisition of fixed assets and operating expenses related to VAT exempt activities. The
Company appealed to the Athens Administrative Court of First Instance on 28 September 2010, against the decision
of the Tax Authority to impose VAT on such expenses and also referred the issue to the London Court of International
Arbitration, together with the issue described in b) above, in accordance with the article 44 of the ADA. The hearing
of the case in front of the Athens Administrative Court of First Instance has not been scheduled so far while the
arbitration process has initiated, in accordance with the time schedule agreed with the London Court of International
Arbitration, and the hearing is scheduled to take place within the second half of the current year 2011. No provision
has been recognised, based on Company’s experts’ opinion by reference to the specific legislation governing its tax
affairs, since no significant liability is expected to materialise. (refer also to note 5.14)
d) With the decision taken on 5 Nov 2009 the Mayor of Peania Municipality requested Company the payment of a total of
€37m for the compensative municipal charges and penalties for the provision for waste, landscaping, cleanliness and
lighting maintenance for the period 1 Jan 2004 to 31 Dec 2009. Management filed a petition with the Administrative
Court of Athens versus the Municipality of Peania, accompanied by corresponding petitions for the deferment of
payment, claiming that in accordance with the provisions of the ADA, AIA has been granted with the exclusive right
to provide such services to airport users. Said deferment of payment has been provisionally granted by order of the
competent judge of the Administrative Court of Athens until the issuance of a Court Decision on the petitions. No
provision has been recognised based on Company’s experts’ opinion by reference to the specific legislation governing
its municipal tax affairs, since the case is expected to be concluded at its favour.
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 47 of 51
c) Operating lease commitments are analysed as follows: 2010 2009
Analysis of operating lease commitments 210,376 203,181
389,524 365,110
Within 1 year
Between 1 and 5 years 599,900 568,291
Total operating lease commitments
5.28 Contingent liabilities
The Company has contingent liabilities comprising the following:
a) The Company has not been audited yet by the Tax Authority for the fiscal years 2004 through to 2010. Consequently,
the tax liability with respect to the fiscal years 2004-2010 has not been finalized yet. Tax Authorities have already
initiated the regular tax audit for the years 2004-2009 which is still in progress. However, management does not
expect any additional income taxes to be paid in view of the existence of significant assessable tax losses available for
carried forward (Refer to note 5.22).
b) During 2005 a tax audit was performed by the Tax Authority for the fiscal years 1998-2003. Income tax and all other
indirect taxes, except VAT, were levied and settled in 2006. With respect to VAT, the Tax Authority questioned the
right of the Company to set off the total VAT of all goods purchased and services rendered, as provided by article
26 paragraph 7 of law 2093/1992, in combination with articles 25.1.1 & 25.1.2 (g) of law 2338/1995 (the Airport
Development Agreement). The Tax Authority disputed the above right of the Company, and proceeded to impose VAT
–including penalties- for the years 1998-2003 of €1,9m, which corresponds to VAT of non-exempt expenses, such as,
entertainment and hospitality expenses. The Company appealed to the Athens Administrative Court of First Instance
on 7 February 2006, against the decision of the Tax Authority to impose VAT on such expenses. The hearing of the
case has not been scheduled so far.
c) In addition, the Tax Authority issued a provisional VAT audit report, for the years 2001-2003, expressing reservation
with respect to the right of the Company to set off VAT, which corresponds to activities not subjected to VAT i.e.
property leases, without imposing any tax. On this reservation, the Tax Authority requested the opinion of the
Ministry of Finance, which finally responded in 2010 considering that the Company has no right to set off the VAT
corresponding to activities not subjected to VAT in accordance with the general provision of the VAT Law (2859/2000)
and the 6th EU Directive. Following the response of the Ministry of Finance the Tax Authority proceeded with the
finalisation of the interim audit report imposing VAT –including penalties- for the years 2001-2003 of €150,3m, which
corresponds to VAT on the acquisition of fixed assets and operating expenses related to VAT exempt activities. The
Company appealed to the Athens Administrative Court of First Instance on 28 September 2010, against the decision
of the Tax Authority to impose VAT on such expenses and also referred the issue to the London Court of International
Arbitration, together with the issue described in b) above, in accordance with the article 44 of the ADA. The hearing
of the case in front of the Athens Administrative Court of First Instance has not been scheduled so far while the
arbitration process has initiated, in accordance with the time schedule agreed with the London Court of International
Arbitration, and the hearing is scheduled to take place within the second half of the current year 2011. No provision
has been recognised, based on Company’s experts’ opinion by reference to the specific legislation governing its tax
affairs, since no significant liability is expected to materialise. (refer also to note 5.14)
d) With the decision taken on 5 Nov 2009 the Mayor of Peania Municipality requested Company the payment of a total of
€37m for the compensative municipal charges and penalties for the provision for waste, landscaping, cleanliness and
lighting maintenance for the period 1 Jan 2004 to 31 Dec 2009. Management filed a petition with the Administrative
Court of Athens versus the Municipality of Peania, accompanied by corresponding petitions for the deferment of
payment, claiming that in accordance with the provisions of the ADA, AIA has been granted with the exclusive right
to provide such services to airport users. Said deferment of payment has been provisionally granted by order of the
competent judge of the Administrative Court of Athens until the issuance of a Court Decision on the petitions. No
provision has been recognised based on Company’s experts’ opinion by reference to the specific legislation governing
its municipal tax affairs, since the case is expected to be concluded at its favour.
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 47 of 51