Page 84 - 2board23full
P. 84
Financial Statements
• If the discount rate used were 1,0% higher, then the DBO would be lower by about €0,8 m
• If the discount rate used were 1,0% lower, then the DBO would be higher by about €1,0 m
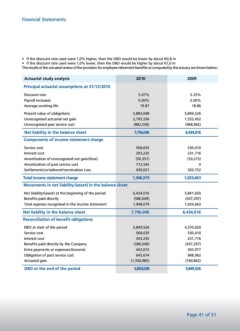
The results of the actuarial review of the provision for employee retirement benefits as computed by the actuary are shown below:
Actuarial study analysis 2010 2009
Principal actuarial assumptions at 31/12/2010 5.25%
3.00%
Discount rate 5.07% 18.86
Payroll increases 0.00% 5,849,526
Average working life 19.87 1,553,452
(968,962)
Present value of obligations 5,883,048
Unrecognised actuarial net gain 2,795,556 6,434,016
Unrecognized past service cost (882,558)
530,410
Net liability in the balance sheet 7,796,046 231,716
Components of income statement charge (53,215)
Service cost 568,635 0
Interest cost 293,235 320,752
Amortization of unrecognised net gain/(loss) (56,357)
Amortization of past service cost 712,545 1,029,663
Settlement/curtailment/termination Loss 430,021
5,841,650
Total income statement charge 1,948,079 (437,297)
1,029,663
Movements in net liability/(asset) in the balance sheet
6,434,016
Net liability/(asset) at the beginning of the period 6,434,016
Benefits paid directly (586,049) 4,370,620
Total expense recognised in the income statement 1,948,079 530,410
231,716
Net liability in the balance sheet 7,796,046
(437,297)
Reconciliation of benefit obligations 345,977
968,962
DBO at start of the period 5,849,526
Service cost 568,635 (160,862)
Interest cost 293,235
Benefits paid directly by the Company 5,849,526
Extra payments or expenses/(income) (586,049)
Obligation of past service cost 443,012
Actuarial gain 645,674
(1,330,985)
DBO at the end of the period 5,883,048
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 41 of 51
• If the discount rate used were 1,0% higher, then the DBO would be lower by about €0,8 m
• If the discount rate used were 1,0% lower, then the DBO would be higher by about €1,0 m
The results of the actuarial review of the provision for employee retirement benefits as computed by the actuary are shown below:
Actuarial study analysis 2010 2009
Principal actuarial assumptions at 31/12/2010 5.25%
3.00%
Discount rate 5.07% 18.86
Payroll increases 0.00% 5,849,526
Average working life 19.87 1,553,452
(968,962)
Present value of obligations 5,883,048
Unrecognised actuarial net gain 2,795,556 6,434,016
Unrecognized past service cost (882,558)
530,410
Net liability in the balance sheet 7,796,046 231,716
Components of income statement charge (53,215)
Service cost 568,635 0
Interest cost 293,235 320,752
Amortization of unrecognised net gain/(loss) (56,357)
Amortization of past service cost 712,545 1,029,663
Settlement/curtailment/termination Loss 430,021
5,841,650
Total income statement charge 1,948,079 (437,297)
1,029,663
Movements in net liability/(asset) in the balance sheet
6,434,016
Net liability/(asset) at the beginning of the period 6,434,016
Benefits paid directly (586,049) 4,370,620
Total expense recognised in the income statement 1,948,079 530,410
231,716
Net liability in the balance sheet 7,796,046
(437,297)
Reconciliation of benefit obligations 345,977
968,962
DBO at start of the period 5,849,526
Service cost 568,635 (160,862)
Interest cost 293,235
Benefits paid directly by the Company 5,849,526
Extra payments or expenses/(income) (586,049)
Obligation of past service cost 443,012
Actuarial gain 645,674
(1,330,985)
DBO at the end of the period 5,883,048
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 41 of 51