Page 76 - 2board23full
P. 76
Financial Statements
According to article 26.1 of law 2338/1995, the “Airport Development Agreement”, the Greek State undertook the
responsibility to collect the passenger fee over the period from 1/11/1994 to 1/11/2014. The Greek State also committed
that article 40 of law 2065/1992 “will not be amended or modified in any respect which materially prejudices the
financial return of the Airport Company”.
Based on the provisions of article 26.2 of law 2338/1995, in conjunction with article 16 of law 2892/2001, the airport
company, at all times prior to airport opening and at all times after the airport opening, is entitled to make withdrawals
from the Spata Airport Development Fund, in order to fund borrowing costs incurred in respect to loans received for
funding infrastructure development.
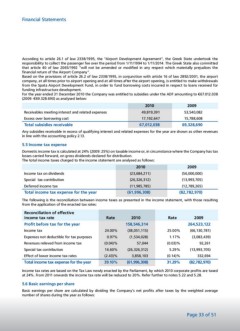
For the year ended 31 December 2010 the Company was entitled to subsidies under the ADF amounting to €67.012.038
(2009: €69.328.690) as analysed below:
2010 2009
Receivables meeting interest and related expenses 49,819,391 53,540,082
Excess over borrowing cost 17,192,647 15,788,608
Total subsidies receivable 67,012,038 69,328,690
Any subsidies receivable in excess of qualifying interest and related expenses for the year are shown as other revenues
in line with the accounting policy 2.13.
5.5 Income tax expense
Domestic income tax is calculated at 24% (2009: 25%) on taxable income or, in circumstance where the Company has tax
losses carried forward, on gross dividends declared for distribution.
The total income taxes charged to the income statement are analysed as follows:
2010 2009
Income tax on dividends (23,684,211) (56,000,000)
Special tax contribution (26,326,312) (13,993,705)
Deferred income tax (11,985,785) (12,789,265)
Total income tax expense for the year (61,996,308) (82,782,970)
The following is the reconciliation between income taxes as presented in the income statement, with those resulting
from the application of the enacted tax rates:
Reconciliation of effective 2010 Rate 2009
income tax rate Rate 264,523,122
Profit before tax for the year 158,546,314 (66,130,781)
(3,083,439)
Income tax 24.00% (38,051,115) 25.00% 92,261
Expenses not deductible for tax purposes 0.97% (1,534,028) 1.17% (13,993,705)
332,694
Revenues relieved from income tax (0.04)% 57,044 (0.03)%
(82,782,970)
Special tax contribution 16.60% (26,326,312) 5.29%
Effect of lower income tax rates (2.43)% 3,858,103 (0.14)%
Total income tax expense for the year 39.10% (61,996,308) 31.29%
Income tax rates are based on the Tax Law newly enacted by the Parliament, by which 2010 corporate profits are taxed
at 24%. From 2011 onwards the income tax rate will be reduced to 20%. Refer further to notes 5.22 and 5.28.
5.6 Basic earnings per share
Basic earnings per share are calculated by dividing the Company’s net profits after taxes by the weighted average
number of shares during the year as follows:
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 33 of 51
According to article 26.1 of law 2338/1995, the “Airport Development Agreement”, the Greek State undertook the
responsibility to collect the passenger fee over the period from 1/11/1994 to 1/11/2014. The Greek State also committed
that article 40 of law 2065/1992 “will not be amended or modified in any respect which materially prejudices the
financial return of the Airport Company”.
Based on the provisions of article 26.2 of law 2338/1995, in conjunction with article 16 of law 2892/2001, the airport
company, at all times prior to airport opening and at all times after the airport opening, is entitled to make withdrawals
from the Spata Airport Development Fund, in order to fund borrowing costs incurred in respect to loans received for
funding infrastructure development.
For the year ended 31 December 2010 the Company was entitled to subsidies under the ADF amounting to €67.012.038
(2009: €69.328.690) as analysed below:
2010 2009
Receivables meeting interest and related expenses 49,819,391 53,540,082
Excess over borrowing cost 17,192,647 15,788,608
Total subsidies receivable 67,012,038 69,328,690
Any subsidies receivable in excess of qualifying interest and related expenses for the year are shown as other revenues
in line with the accounting policy 2.13.
5.5 Income tax expense
Domestic income tax is calculated at 24% (2009: 25%) on taxable income or, in circumstance where the Company has tax
losses carried forward, on gross dividends declared for distribution.
The total income taxes charged to the income statement are analysed as follows:
2010 2009
Income tax on dividends (23,684,211) (56,000,000)
Special tax contribution (26,326,312) (13,993,705)
Deferred income tax (11,985,785) (12,789,265)
Total income tax expense for the year (61,996,308) (82,782,970)
The following is the reconciliation between income taxes as presented in the income statement, with those resulting
from the application of the enacted tax rates:
Reconciliation of effective 2010 Rate 2009
income tax rate Rate 264,523,122
Profit before tax for the year 158,546,314 (66,130,781)
(3,083,439)
Income tax 24.00% (38,051,115) 25.00% 92,261
Expenses not deductible for tax purposes 0.97% (1,534,028) 1.17% (13,993,705)
332,694
Revenues relieved from income tax (0.04)% 57,044 (0.03)%
(82,782,970)
Special tax contribution 16.60% (26,326,312) 5.29%
Effect of lower income tax rates (2.43)% 3,858,103 (0.14)%
Total income tax expense for the year 39.10% (61,996,308) 31.29%
Income tax rates are based on the Tax Law newly enacted by the Parliament, by which 2010 corporate profits are taxed
at 24%. From 2011 onwards the income tax rate will be reduced to 20%. Refer further to notes 5.22 and 5.28.
5.6 Basic earnings per share
Basic earnings per share are calculated by dividing the Company’s net profits after taxes by the weighted average
number of shares during the year as follows:
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 33 of 51