Page 70 - 2board23full
P. 70
Financial Statements
The impact from possible future interest rates on the Company’s financial performance from the settlement of the
financial assets is presented in note 5.3 “Net financial expenses”.
c)Price risk
Price risk is the risk of fluctuations in the value of assets and liabilities as a result of changes in market prices. The
Company’s exposure to equity securities price risk is limited to the investment in an unlisted entity which represents less
than 1% of total asset. The Company is not exposed to commodity price risk.
d) Credit risk
Credit risk arises from cash and cash equivalents held with banks and credit exposures from customers.
Cash and cash equivalents
For banks and financial institutions, only independently rated parties with minimum ratings described below, as set out
under the Master Facility Agreement between the Company and the EIB, are acceptable. The Company could cooperate
with banks or financial institutions that satisfy the following criteria:
• Long term unsecured and unguaranteed debt should be rated at:
a. A3 or higher by Moody’s; or
b. A- or higher by S&P; or
c. A- or higher by Fitch
• Operates a branch in Greece or such other places as may be agreed between the Company and EIB; and
• Is acceptable by EIB
Although for most of the cooperating banks the credit ratings are lower than the provision of Master Facility Agreement,
the Company has been granted approval by EIB to continue the cooperation with these banks. The Company cooperates
with the following banks: UniCredit Bank AG, Alpha Bank, EFG Eurobank Ergasias, Emporiki Bank, Piraeus Bank, HSBC and
National Bank of Greece. The Moody’s credit rating for senior unsecured debt for these banks varies from Aa1 to Baa3.
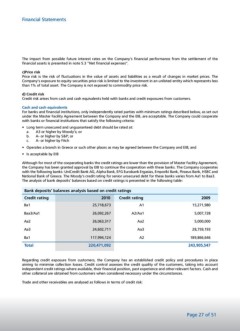
The analysis of bank deposits’ balances based on credit ratings is presented in the following table:
Bank deposits’ balances analysis based on credit ratings
Credit rating 2010 Credit rating 2009
Ba1 25,718,673 A1 15,271,980
5,007,728
Baa3/Aa1 26,092,267 A2/Aa1 5,000,000
Aa2 26,063,317 Aa2 28,759,193
189,866,646
Aa3 24,602,711 Aa3
243,905,547
Ba1 117,994,124 A2
Total 220,471,092
Regarding credit exposure from customers, the Company has an established credit policy and procedures in place
aiming to minimise collection losses. Credit control assesses the credit quality of the customers, taking into account
independent credit ratings where available, their financial position, past experience and other relevant factors. Cash and
other collateral are obtained from customers when considered necessary under the circumstances.
Trade and other receivables are analysed as follows in terms of credit risk:
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 27 of 51
The impact from possible future interest rates on the Company’s financial performance from the settlement of the
financial assets is presented in note 5.3 “Net financial expenses”.
c)Price risk
Price risk is the risk of fluctuations in the value of assets and liabilities as a result of changes in market prices. The
Company’s exposure to equity securities price risk is limited to the investment in an unlisted entity which represents less
than 1% of total asset. The Company is not exposed to commodity price risk.
d) Credit risk
Credit risk arises from cash and cash equivalents held with banks and credit exposures from customers.
Cash and cash equivalents
For banks and financial institutions, only independently rated parties with minimum ratings described below, as set out
under the Master Facility Agreement between the Company and the EIB, are acceptable. The Company could cooperate
with banks or financial institutions that satisfy the following criteria:
• Long term unsecured and unguaranteed debt should be rated at:
a. A3 or higher by Moody’s; or
b. A- or higher by S&P; or
c. A- or higher by Fitch
• Operates a branch in Greece or such other places as may be agreed between the Company and EIB; and
• Is acceptable by EIB
Although for most of the cooperating banks the credit ratings are lower than the provision of Master Facility Agreement,
the Company has been granted approval by EIB to continue the cooperation with these banks. The Company cooperates
with the following banks: UniCredit Bank AG, Alpha Bank, EFG Eurobank Ergasias, Emporiki Bank, Piraeus Bank, HSBC and
National Bank of Greece. The Moody’s credit rating for senior unsecured debt for these banks varies from Aa1 to Baa3.
The analysis of bank deposits’ balances based on credit ratings is presented in the following table:
Bank deposits’ balances analysis based on credit ratings
Credit rating 2010 Credit rating 2009
Ba1 25,718,673 A1 15,271,980
5,007,728
Baa3/Aa1 26,092,267 A2/Aa1 5,000,000
Aa2 26,063,317 Aa2 28,759,193
189,866,646
Aa3 24,602,711 Aa3
243,905,547
Ba1 117,994,124 A2
Total 220,471,092
Regarding credit exposure from customers, the Company has an established credit policy and procedures in place
aiming to minimise collection losses. Credit control assesses the credit quality of the customers, taking into account
independent credit ratings where available, their financial position, past experience and other relevant factors. Cash and
other collateral are obtained from customers when considered necessary under the circumstances.
Trade and other receivables are analysed as follows in terms of credit risk:
Financial Statements as at 31 December 2010 (Amounts in Euros unless otherwise stated) Page 27 of 51